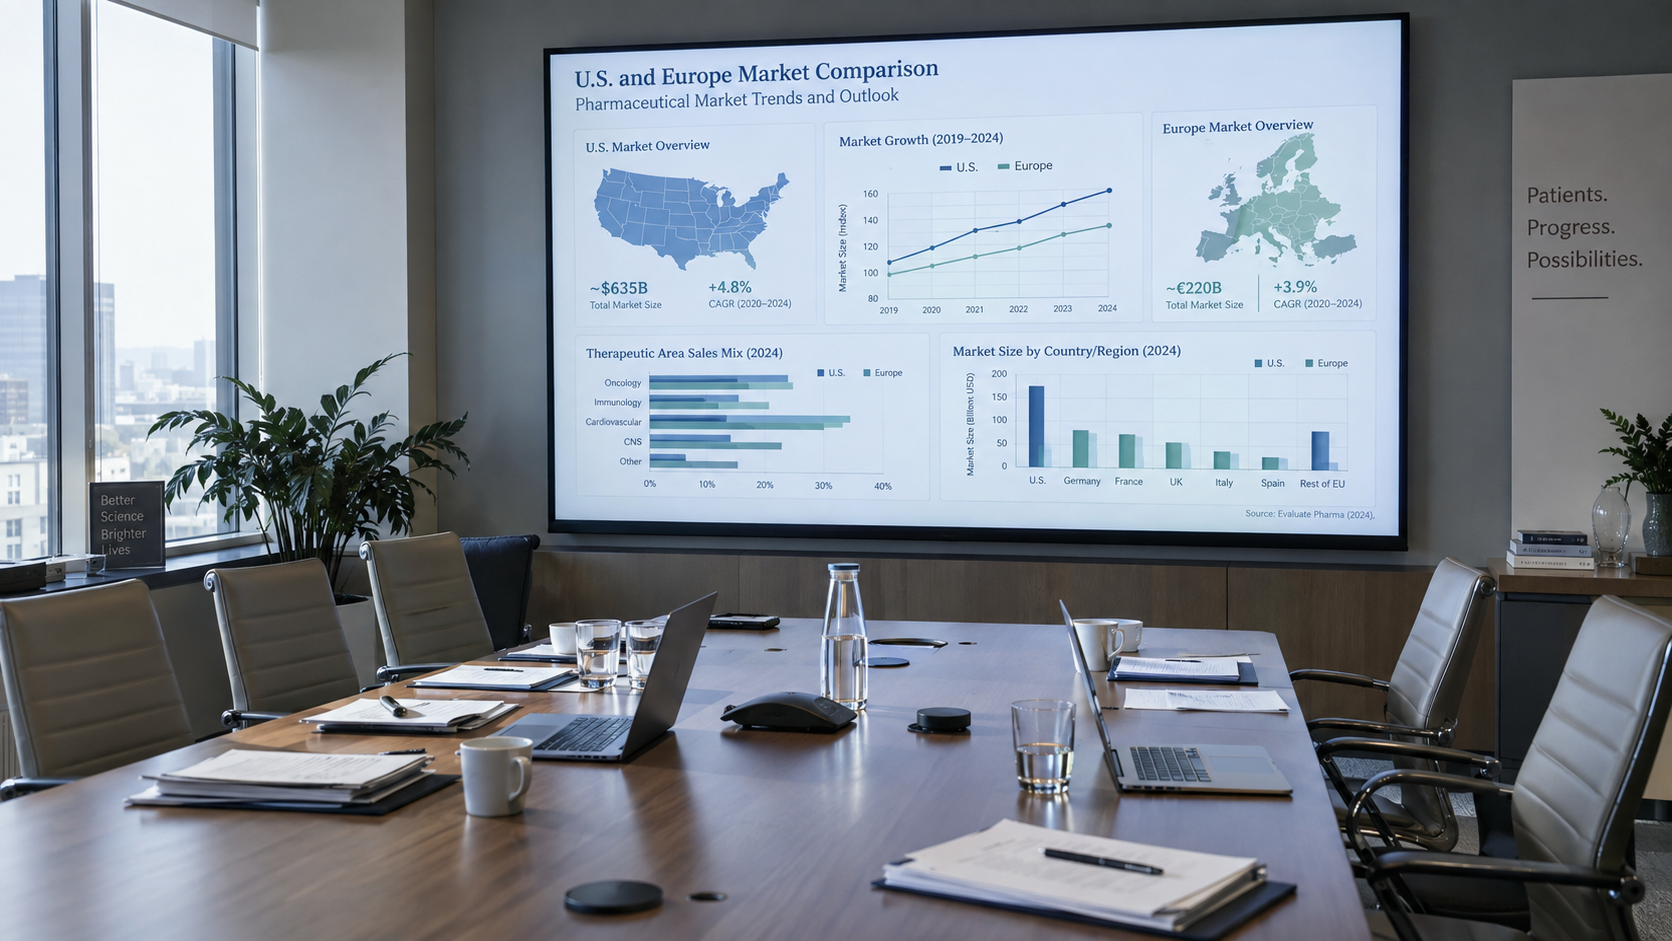
Most-Favored-Nation Pricing Is Becoming a Global Management Problem
The expansion of the GENEROUS Medicaid model and newly disclosed terms in Pfizer’s U.S. pricing agreement show how decisions about pharmaceutical pricing outside the United States can increasingly affect U.S. reimbursement and company economics. Global pricing decisions may need to be managed with a much wider lens.
For pharmaceutical companies, the latest U.S. drug-pricing developments are getting harder to look at one at a time.
President Trump announced that all 50 states, Washington, D.C. and Puerto Rico intend to participate in the GENEROUS Medicaid model. The program is designed to give Medicaid access to net prices for certain medicines that are comparable to prices paid in selected foreign countries.
At the same time, newly released contract language involving Pfizer reportedly shows that the company agreed to share with the Department of Health and Human Services a portion of additional net revenue generated when prices for certain medicines increase outside the United States.
Those two developments matter together because they show how pricing decisions made in Europe and other markets can affect U.S. reimbursement and U.S. government agreements.
GENEROUS Brings International Pricing Into Medicaid
The immediate importance of GENEROUS is its reach. Every state has now expressed interest in participating in a model that uses international pricing as part of the way Medicaid rebates are calculated for participating medicines.
That does not mean every drug suddenly gets an international reference price. Manufacturers still have to participate, products will differ, and many of the details matter. But there is enough here for management teams to pay attention.
A price negotiated in Europe or another reference market may affect the economics of the same product in the United States. That makes it harder to treat global pricing as a collection of separate country-by-country decisions.
The Pfizer Agreement Adds Another Layer
The Pfizer disclosure makes the issue more interesting.
According to the reported contract language, Pfizer must share with HHS part of the additional revenue generated when prices for certain medicines rise outside the United States. The public version does not reveal the percentage, the covered medicines or several other important terms.
Even with those gaps, the structure is worth watching.
A higher price overseas could improve revenue in that market while also creating a separate financial obligation in the United States. That is different from a traditional reference-pricing model, where the main concern is how a foreign price may affect a U.S. benchmark.
Here, a commercial decision in one country may create an economic consequence somewhere else.
This Is a Management Issue
That is why this is becoming more than a pricing issue.
The practical management question is whether the company understands which decisions made outside the United States can affect its U.S. economics.
That requires market access, finance, legal, government affairs and commercial teams to work from the same picture. Each group may be making a reasonable decision on its own, but problems can arise when those decisions are made without understanding what they mean for another market.
A locally successful pricing decision can still create an unexpected consequence elsewhere.
What Management Should Be Looking At
Companies should start by mapping their major products against the pricing arrangements that could matter in the United States. Management should understand which international prices could affect GENEROUS or other U.S. pricing arrangements, which products are covered by company-specific agreements, and what happens when the price of a medicine changes in another market.
There should also be a clear process for bringing pricing, legal, finance, government affairs and commercial leadership together before a significant pricing decision is made.
The goal is not to predict every future policy change. It is to make sure a decision in one market does not create an expensive surprise in another.
The Bigger Picture
There is still a lot we do not know. Many of the pharmaceutical agreements being negotiated with the administration remain confidential, and some of the most important commercial terms have not been made public.
But companies already have enough information to see the broader issue.
International pricing is becoming more closely tied to U.S. reimbursement. GENEROUS does that through Medicaid rebates linked to prices in other countries. The Pfizer agreement reportedly adds another connection by tying increases in overseas revenue to payments back to HHS.
For executives, the question is becoming less about what price should be negotiated in a particular country and more about what that decision does to the economics of the product across markets.
That is the issue management teams should be thinking about now.
About Lanton Strategies International & Lanton, Lanton and Sosa Law, PLLC
Lanton Strategies International works with executives and organizations on policy, market access, government affairs and strategic issues affecting investment, commercialization and growth across the United States and Europe. We help leadership teams understand what policy developments mean for their business and determine practical next steps.
For legal and regulatory matters, Lanton, Lanton & Sosa Law PLLC advises companies on issues affecting healthcare, life sciences, technology, commercialization and business strategy.
This article is provided for informational and educational purposes only and should not be relied upon as legal, investment or other professional advice. Reading it does not create an attorney-client relationship.
Trump’s New EU Tariff Threat Creates Another Planning Problem for CEOs
President Trump’s latest tariff threat toward Europe adds another layer of uncertainty for companies making decisions about manufacturing, supply chains and cross-border investment. The right response is not panic. It is understanding exposure, testing assumptions and preserving flexibility before uncertainty becomes an expensive business problem.
European executives making decisions about U.S. manufacturing, sourcing and capital deployment have another variable to consider.
On September 17, 2026, President Donald Trump threatened heavier tariffs on Europe if the European Union moves ahead with a proposal to create a closer relationship with Canada. Canadian Prime Minister Mark Carney has called for deeper cooperation with Europe in areas including trade, technology, energy and critical minerals. Reuters Financial Times
The proposed EU–Canada relationship is not fully defined, and there is no new tariff schedule to model today. Companies should not redesign their businesses around every political statement.
They also cannot ignore the possibility that trade conditions between the United States, Europe and Canada could become less predictable. That uncertainty is the real issue.
For a European company considering a U.S. facility, a major sourcing decision or a new market entry, the question is simple:
Which assumptions become expensive if they are wrong?
That is where management should focus. A company should understand how different tariff scenarios could affect the economics of a new investment, where its supply chain is most exposed, which decisions can wait and where flexibility should be preserved. The best response is not panic. It is scenario planning.
The Canada–EU relationship matters even before the details are settled
The EU’s proposal is broader than a conventional trade discussion. The emerging relationship could involve cooperation in technology, healthcare, energy, security, critical minerals, digital trade, research and other strategic areas.
For companies, that may create opportunities as well as risks. Closer Canada–EU cooperation could lead to new partnerships, sourcing options and investment relationships, particularly in healthcare, technology, advanced manufacturing and critical materials.
At the same time, a stronger Canada–EU relationship could produce new questions for businesses that operate across all three markets. Which rules will apply? Will supply chains become more diversified or more complicated? Could political retaliation affect investment decisions, customs treatment or market access?
Those questions require companies to understand the actual structure of their operations and the assumptions behind major commitments.
The business consequence matters more than the political prediction
CEOs do not need to predict whether Canada ultimately receives a new relationship with the EU or whether Washington follows through on additional tariffs.
They need to know what each plausible outcome could mean for the business.
That means identifying exposure across manufacturing, sourcing, logistics, contracts, data, financing, regulatory approvals and customer commitments.
It also means separating decisions that require action now from decisions that should remain flexible until more is known. Political signals can change quickly. Factories, contracts, supply chains and capital commitments cannot.
What executives should review now
Leadership teams should begin by mapping which products, services and investments depend on the United States, Europe or Canada. They should identify where goods cross borders, where important inputs originate and which contracts assume stable tariff or regulatory conditions.
They should also test whether a proposed investment still makes sense under several scenarios. A project that works under current assumptions may look different if tariffs increase, customs treatment changes or a company loses access to a preferred supplier.
The exercise does not require predicting the future. It just simply requires understanding the cost of being incorrect.
Companies should also review whether their contracts address tariff changes, regulatory shifts, supply interruptions, delays, force majeure, price adjustments and termination rights. These provisions may become more important as trade policy becomes less predictable.
A planning problem, not a reason to freeze
Uncertainty can cause companies to delay decisions unnecessarily. That can be just as costly as moving too quickly.
The goal is not to stop investing, entering markets or building relationships. The goal is to understand which decisions are durable, which can be staged and which should preserve room to adapt.
A company may decide to proceed with a facility but phase the investment. It may retain more than one supplier. It may structure a contract with clearer adjustment mechanisms. It may test a market before making a larger commitment. Those are practical and measured responses to uncertainty.
The lesson for CEOs
The current dispute over Canada, the European Union and possible U.S. tariffs is part of a larger change in the business environment. Executives are planning around movement, not around a stable set of trade and regulatory assumptions.
The practical lesson is straightforward: separate the headline from the business consequence.
Understand where the exposure sits. Test the assumptions behind major decisions. Review the contracts that support those decisions. Preserve enough flexibility to move if the policy environment changes.
Lanton Strategies International works with executives and organizations on policy, market access, government affairs and strategic issues affecting investment, commercialization and growth across the United States and Europe. We help leadership teams understand what policy developments mean for their business and determine practical next steps.
For legal and regulatory matters, Lanton, Lanton & Sosa Law PLLC advises companies on issues affecting healthcare, life sciences, technology, commercialization and business strategy.
This article is provided for informational and educational purposes only and should not be relied upon as legal, investment or other professional advice. Reading it does not create an attorney-client relationship.
When Drug Pricing Policy Starts to Shape Where Medicines Are Made
European drugmakers considering U.S. manufacturing must weigh trade pressure, incentives, reimbursement and launch strategy alongside ordinary production costs.
For years, European pharmaceutical companies have treated manufacturing location as an operational decision. That is changing.
Ipsen is reportedly considering a U.S. manufacturing site while continuing to expand production in the United Kingdom. The company has not made a final decision, but the question itself reflects a broader shift facing European drugmakers. The Wall Street Journal, September 11, 2026
A company deciding where to manufacture a medicine now has to consider more than labor, capacity and logistics. It must also think about tariffs, domestic-production incentives, political pressure, reimbursement rules and the order in which products should be launched in different markets.
A U.S. facility may help a company respond to trade demands or qualify for incentives. It may also bring higher construction and operating costs. Building in Europe may preserve existing expertise and infrastructure, while exposing the company to a different set of political and commercial risks.
The decision becomes even more complicated when a product is approaching launch. A company may have to determine whether the economics justify a new facility, a contract manufacturing arrangement, an acquisition or an expansion of an existing site. Each option affects capital allocation, regulatory planning and the timing of market entry.
This is not only a question for the largest pharmaceutical companies. Smaller biotechs and specialty manufacturers may face the same choice earlier in their development cycle because investors and strategic partners want to know where production will occur and how resilient the supply chain will be.
The larger point is that drug pricing policy is beginning to influence industrial policy. Decisions about reimbursement and market access can affect where companies build, where they hire and where they place their next dollar of investment.
For European life-sciences companies looking toward the United States, manufacturing strategy can no longer be separated from policy strategy.
International Arbitration Should Be Planned Before a Dispute
Cross-border disputes are easier to manage when companies address arbitration during contract negotiations. This article explains the key decisions businesses should consider, including the arbitration clause, governing law, legal seat, enforcement, and emergency relief.
When a cross-border business relationship breaks down, the parties often begin arguing about more than the underlying problem. They may also disagree about where the dispute belongs, which law applies, who should decide it, and whether an eventual decision can be enforced.
Those questions are easier to manage when they are addressed during contract negotiations.
A well-drafted arbitration clause should identify the disputes covered, the governing rules, the legal seat of the arbitration, the language of the proceeding, and how the arbitrator will be selected. A sentence stating that disputes “will be resolved by arbitration” may not provide enough direction when the parties need it most.
The legal seat is especially important. It determines the procedural law governing the arbitration and the courts that may supervise the proceeding or review the award. It is not necessarily the same as the physical location of hearings.
The parties should also distinguish between governing law and arbitral seat. Governing law generally addresses the substance of the contract. The seat addresses the legal framework for the arbitration. Choosing one does not automatically resolve the other.
Enforcement should be considered at the beginning, not after an award is issued. A successful party must be able to enforce the award where the opposing party has assets. The countries involved, the location of property, and the applicable enforcement framework can all affect the practical value of arbitration.
The agreement should also account for urgent situations involving confidential information, intellectual property, critical assets, or other harm that cannot be repaired through a later damages award. The selected rules may provide access to emergency or interim relief, but the parties should understand those options in advance.
International arbitration is not automatically faster or less expensive than litigation. Its value depends on the contract, the jurisdictions involved, the facts of the dispute, and how the proceeding is managed.
For companies operating across borders, arbitration should be treated as part of commercial risk planning—not as a clause added at the end of a contract.
At Lanton, Lanton & Sosa Law, we advise businesses and organizations on cross-border contracts, dispute strategy, employment matters, and international arbitration.
This article is for educational purposes only and does not constitute legal advice.
#InternationalArbitration #CrossBorderBusiness #CommercialDisputes #ContractDrafting
AI + Healthcare, Part 2: What Happens When the Product Keeps Changing After Approval?
FDA approval is not the end of the regulatory or commercial journey for AI-enabled healthcare products. This article examines what happens when AI changes a medical device, diagnostic tool or clinical software platform after approval—and how companies should manage regulatory review, reimbursement, accountability and investor expectations.
The harder regulatory question may begin after FDA clearance or approval.
A medical device, diagnostic tool or clinical software platform may reach the market based on one version of its technology. The company then uses AI to improve performance, identify new patterns, reduce false positives or expand the product’s usefulness.
That creates a new practical question for leadership: when is an update still part of the approved product, and when has the company created something that needs another regulatory review?
A conventional medical product usually stays recognizable after approval. Its manufacturer may improve the design, but providers, payers and regulators can still identify the product they evaluated and compare the changes against the earlier version.
AI-enabled software can change things more quietly. A new training set, algorithm or software release may alter the product’s recommendations without changing its outward appearance. The company’s process for managing those changes therefore should become part of its regulatory strategy.
For example, an update that fixes a technical problem may raise different questions from one that changes the product’s intended use, clinical claims, risk profile or method of operation. A diagnostic tool that becomes capable of identifying a different condition, guiding a new treatment decision or serving a broader patient population may require more than ordinary maintenance.
Executives should establish those boundaries before the product reaches the market. Waiting until an engineering team has completed a major update can leave the company trying to answer regulatory questions after the commercial decision has already been made.
Approval does not end the regulatory work
AI development often follows a continuous cycle. Teams release improvements in response to new data, customer feedback and performance testing. FDA review, however, is based on defined submissions and defined evidence.
A company needs a practical plan for what happens next. It should know which changes can be handled through an established change-control process, which require additional validation and which may require a new submission. It should also be able to show how the updated product performs across the populations and care settings where it will be used.
This does not require companies to abandon rapid development. It requires technical, clinical and regulatory teams to make decisions together before an update is released.
Payment and adoption create a second gate
FDA authorization allows a product to be marketed under the applicable rules. It does not guarantee coverage, payment or adoption.
An AI update may improve accuracy or expand the number of patients who can benefit. A payer may still ask whether the change improves outcomes, lowers total cost or simply produces a more sophisticated recommendation.
Hospitals may ask whether the update changes workflow, documentation, staffing or liability. Health plans may ask whether the revised product fits within an existing coverage category or requires new evidence.
A company that treats reimbursement as a post-approval issue may discover that its commercial plan has not kept pace with its regulatory progress.
Responsibility follows the update
Leadership also needs a clear answer to a basic question: who is responsible when the product changes?
That answer depends on how the company tests and validates each release, notifies providers and customers, maintains version records and manages human review.
It also depends on cybersecurity, data governance and the contracts that allocate responsibility among the developer, provider and health system.
If the system produces a different result after receiving new data, the company should be able to explain what changed, why it changed and how the revised performance was evaluated.
That is a business requirement as much as a legal one.
The investment question
Investors may see continuous AI improvement as a competitive advantage. They may also ask whether the company has the systems needed to manage continuing FDA, reimbursement, quality and liability obligations.
A company that can show disciplined product governance may be better positioned than one that treats every update as a software release with no regulatory consequences. The quality of that governance can affect launch timing, contracting, payer discussions and investor confidence.
The central issue is not whether AI should continue improving after approval. It should.
The issue is whether the company has built a process that allows improvement without losing track of authorization, evidence, payment and accountability.
FDA approval marks an important milestone. For an AI-enabled product, it may also mark the beginning of a more demanding operating phase.
The companies most likely to succeed will connect engineering, regulatory, clinical, reimbursement and legal decisions before an update reaches the market.
That is the real test for healthcare AI should not be simply whether the product can learn, but whether the company can govern what it learns.
This is the second article in a series examining artificial intelligence through healthcare, regulation, reimbursement, capital and the institutions that determine whether innovation reaches patients.
Lanton Strategies International advises healthcare and life-sciences companies on U.S. market entry, policy, reimbursement, regulatory strategy and commercial risk. Lanton, Lanton & Sosa Law PLLC provides legal counsel to regulated healthcare organizations, associations and businesses.
This article is provided for general educational and informational purposes only. It is not legal advice and does not create an attorney-client relationship. Readers should consult qualified counsel about their specific circumstances.
When Drug Pricing Becomes Trade Policy
Drug pricing is no longer only a reimbursement issue. International price benchmarks, trade policy, manufacturing decisions and market access increasingly affect one another. Healthcare companies need a unified strategy before decisions made in one market create unexpected risks elsewhere.
An earlier version of this analysis was published by Pharmaceutical Executive on August 19, 2026. Read the full Pharmaceutical Executive article.
Drug pricing is no longer only a reimbursement issue. A price negotiated in one country can influence a benchmark in another. A manufacturing decision can affect tariff exposure, regulatory timing and government leverage. A launch strategy that once belonged primarily to a commercial team can now create consequences for finance, legal, market access and public policy.
That is the central argument of my recent Pharmaceutical Executive article, “When Drug Pricing Becomes Trade Policy.” The larger management lesson is straightforward: companies need a complete view of choices that have traditionally been divided among separate teams.
The old boundaries are breaking down
For years, pharmaceutical companies often handled European pricing, U.S. reimbursement, trade policy, manufacturing and government affairs through different teams. That approach becomes risky when a choice in one area changes the company’s exposure somewhere else.
The United States is using international price comparisons in payment policy while also examining foreign pricing systems through trade law. Manufacturing commitments can influence tariff treatment. Regulatory incentives can add time and value considerations to choices about where a product is produced.
There may be no single rule tying these policies together, but management still needs to understand how they affect the same product and business strategy.
The order of market launches now carries greater risk
Companies have always considered market size, expected price, patient access and launch cost when deciding where to introduce a product. International benchmarking and trade scrutiny add another layer.
A lower price in one market may later become relevant to a U.S. benchmark or another government negotiation. Delaying a launch can preserve pricing flexibility, but it can also postpone patient access and revenue. The right answer will differ by product and country. The mistake is allowing each market to make that choice without understanding the global consequences.
Where a company manufactures now affects more than operations
Manufacturing strategy has traditionally centered on capacity, labor, taxes, quality, supply-chain resilience and proximity to important markets. Trade and regulatory policy are adding new variables.
A company evaluating U.S. manufacturing may need to consider tariff treatment, government commitments and whether regulatory timing could affect the value of the investment. This does not mean policy incentives should override the business case. It means the business case is incomplete if those incentives and exposures are ignored.
The C-suite needs a complete view
Pricing cannot remain only with market access. Trade cannot remain only with customs counsel. Manufacturing cannot remain only with operations. Government affairs cannot be limited to monitoring developments after major commitments have already been made.
Management needs a clear way to connect product prices, launch dates, manufacturing locations, major rebates, government commitments and the rules that could affect them. That information should guide operating choices as well as acquisitions, licensing arrangements and capital projects.
Investors and boards should ask whether a product’s pricing history, launch sequence and manufacturing footprint add value, limit flexibility or create risks that have not been modeled. A traditional regulatory review may not reveal those connections unless the diligence process is designed to find them.
Preparation matters more than prediction
No management team can predict every final rule, trade action or negotiated agreement. The practical goal is to preserve flexibility and identify where one choice can change exposure elsewhere.
Companies should establish a senior review process for material pricing, launch and manufacturing commitments. They should stress-test major products against multiple policy scenarios and update the analysis as the rules develop.
The purpose is not to slow the business. It is to prevent different teams from optimizing their own part of the company while unintentionally creating risk somewhere else.
Drug pricing has become part of a wider discussion about trade, industrial policy, manufacturing, patient access and investment. Companies that understand those connections early will be better positioned to act before policy begins to limit their options.
How LSI helps
Lanton Strategies International helps healthcare and life-sciences companies understand how policy, reimbursement, market access and trade developments affect commercial strategy across the United States, Europe and the United Kingdom.
We help management identify risks early, preserve flexibility and make practical choices before changing rules begin to limit their options.
Full analysis: When Drug Pricing Becomes Trade Policy
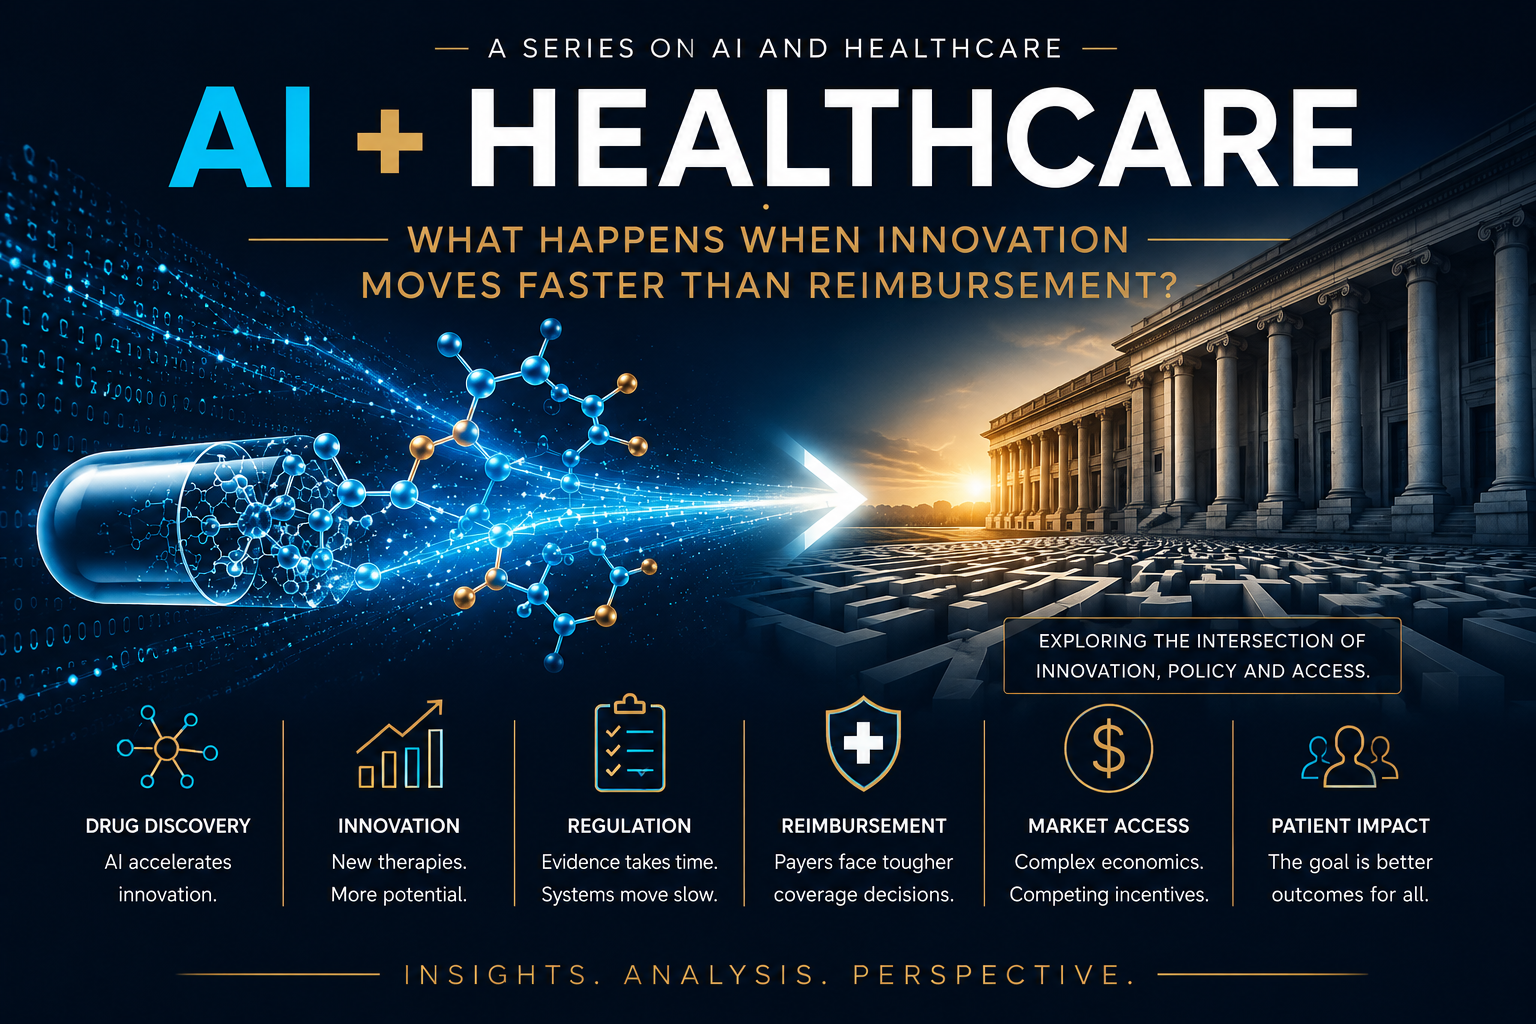
What Happens When AI Develops Drugs Faster Than Insurers Can Figure Out How to Pay for Them?
Artificial intelligence could accelerate drug development, but the healthcare payment system was built to move much more slowly. Using Sovaldi as an early example of what happens when breakthrough innovation collides with reimbursement, Ron Lanton examines whether insurers and other healthcare institutions are prepared for an AI-driven drug pipeline.
In 2013, Sovaldi gave the healthcare system a glimpse of what happens when medical innovation moves faster than the system designed to pay for it.
The drug changed the treatment of hepatitis C. Patients who once faced years of chronic disease suddenly had access to a therapy capable of curing it in a matter of weeks.
Then came the price.
A typical 12-week course cost $84,000.
The debate that followed was not simply about whether Sovaldi worked. Payers had to determine how to cover an expensive breakthrough therapy for a large patient population while operating within existing budgets, formularies, and utilization controls.
More than a decade later, artificial intelligence could create a much bigger version of that problem.
AI is beginning to play a role throughout drug development. It can help identify targets, generate potential molecules, optimize candidates, analyze data, and potentially shorten parts of a process that has traditionally taken years.
That is exciting, but it also exposes a weakness in the healthcare system.
Our ability to create new therapies may eventually begin moving faster than our ability to figure out how to pay for them.
Healthcare reimbursement was built to move carefully. Insurers rely on formularies, pharmacy and therapeutics committees, prior authorization, contracting, benefit design, and annual budgeting. Government programs operate through their own regulatory and budget processes.
There are good reasons for that structure. Evidence has to be reviewed and healthcare spending is not unlimited.
The problem is that the system was built around a relatively slow innovation cycle.
AI could change that cycle without changing the institutions surrounding it.
If AI allows more promising therapies to move through development, insurers may face more coverage decisions, potentially arriving faster and involving products with very different economics.
Sovaldi showed us how difficult one major therapeutic breakthrough could be for the payment system.
AI could make that challenge more common.
There is another issue that AI does not solve.
A treatment may save the healthcare system enormous amounts of money over time while still creating an immediate problem for the payer covering it today.
Imagine a therapy that costs $150,000 but prevents $500,000 in medical expenses over the next 15 years.
That may make sense from a societal perspective.
The insurer paying the $150,000 today may not cover that patient five years from now. An employer may change health plans. A Medicaid patient may move into another program. Medicare may eventually become responsible for that patient’s care.
The organization paying for the innovation may never capture much of the savings it creates.
AI could make drug discovery more efficient. That does not automatically mean drugs will become cheaper, and it does not fix the way we finance long-term value.
That may become one of the most important healthcare questions surrounding AI.
We spend a lot of time talking about what artificial intelligence may allow us to create.
We should also be thinking about whether the institutions surrounding healthcare can keep up with what we create.
Sovaldi forced the system to confront that problem one breakthrough drug at a time.
AI could force us to confront it across the entire system.
This is the first in a series looking at artificial intelligence through healthcare, regulation, reimbursement, capital, and the institutions that ultimately determine whether innovation reaches patients.
When Capital Comes Back, Which Healthcare Companies Will Be Ready?
Global IPO activity is showing signs of renewed momentum, including in biotech. But for healthcare companies, financial readiness is only part of the story. Regulatory, reimbursement and policy risk can quickly become valuation risk when public investors start looking closely at the business.
There are signs that the IPO market is coming back.
EY's latest Global IPO Trends report says momentum strengthened during the first half of 2026, with investor demand appearing across several sectors, including biotech. The UK is also showing early signs of recovery after a difficult period for new listings.
That is encouraging news for healthcare and life sciences companies that have spent the last several years waiting for capital markets to improve.
But an open IPO window does not necessarily mean a company is ready to walk through it.
For healthcare, there is another question executives should be asking: How well will our regulatory, reimbursement and policy assumptions hold up when public investors start looking closely at the business?
Capital is only part of the story
Earlier this year, I explored this issue in Episode 4 of The Ron Lanton Report: From Innovation to Infrastructure: What Gets Funded, What Gets Built.
The basic idea was that innovation alone does not determine what ultimately succeeds in healthcare. Capital flows toward companies that can turn an idea into something the healthcare system can actually support.
The improving IPO environment puts that question back on the table.
EY's analysis is particularly interesting because it describes an IPO market where capital is available, but the windows to access it can still be short. Companies therefore need to be ready before the opportunity appears.
For healthcare companies, readiness means more than audited financial statements and a compelling investor presentation.
It also means understanding the policy assumptions underneath the revenue story.
Investors will look beneath the growth forecast
Consider a biotech company preparing for the public markets.
Its valuation may depend on assumptions about FDA approval, reimbursement, launch timing and the prices its products can command in major markets.
Those assumptions are becoming more complicated.
Drug pricing is now intersecting with trade policy. MFN could change international pricing assumptions. The Inflation Reduction Act continues to influence product economics in the United States. European reimbursement decisions can affect global launch strategies.
A company can have excellent science and still face questions about whether its commercial assumptions will hold.
The same applies outside biopharma.
A digital health company may have strong adoption but still depend on reimbursement policies that could change.
A specialty pharmacy may be growing rapidly while facing PBM network pressure or limited distribution constraints.
A diagnostics company may have compelling technology but still need payer coverage before widespread adoption becomes possible.
Those are not simply regulatory issues.
They can become valuation issues.
Healthcare IPO readiness is becoming broader
This is where I think healthcare executives need to think differently about IPO readiness.
The traditional question is whether the company is financially and operationally prepared to become public.
That remains essential.
But healthcare companies should also be asking whether they can explain the external environment surrounding their business.
What happens if reimbursement changes?
How exposed is the business to one payer, government program or regulatory decision?
Could a policy development change the company's pricing assumptions?
Does international expansion introduce another layer of regulatory or geopolitical risk?
These are questions companies should understand before investors start asking them.
The window may not stay open forever
EY makes another point worth paying attention to: IPO windows can still be episodic.
Geopolitics, large offerings and changes in investor sentiment can quickly alter market conditions.
That means healthcare companies waiting for the perfect market may be thinking about the problem backwards.
The time to prepare for an IPO window is not when everyone agrees that the window has opened.
It is before that happens.
At Lanton Strategies International, this is one of the intersections we watch closely. Capital strategy in healthcare cannot be separated completely from reimbursement, regulation, trade and government policy because those forces ultimately influence the assumptions investors make about growth.
The capital markets may be getting healthier.
For healthcare companies thinking about an IPO, the more important question is whether the business is ready when investors come looking.
Because when the window opens, there may not be much time to get ready.
Independent analysis from Lanton Strategies International. This article does not constitute legal or investment advice.
Is Washington Building a Blueprint for MFN Through Trade Policy?
Washington's Section 301 investigation into German pharmaceutical pricing may be about more than a trade dispute. If the U.S.–UK pharmaceutical agreement becomes a model for Germany, trade policy could become part of a broader strategy for narrowing international drug price differences and pursuing the economic goals behind MFN.
Something interesting is happening in pharmaceutical policy, and executives should be paying attention.
We are hearing growing calls for Washington to pursue an agreement with Germany similar to the U.S.–UK pharmaceutical arrangement as part of the ongoing Section 301 investigation into German drug pricing.
At first glance, this looks like another trade dispute. The bigger question is whether we are beginning to see a potential blueprint for pursuing the goals behind Most Favored Nation drug pricing.
What is happening?
In June, the U.S. Trade Representative opened a Section 301 investigation into Germany's pharmaceutical pricing and reimbursement practices. USTR wants to determine whether what it calls Germany's “persistent underpayment” for innovative medicines is unreasonable or discriminatory and burdens U.S. commerce.
That is unusual because Section 301 is a trade enforcement tool. Germany's drug reimbursement system, on the other hand, is part of its domestic healthcare system.
The U.S. is essentially asking whether decisions made inside another country's healthcare system can create an unfair burden on American commerce.
Now comes the interesting part. Rather than simply looking toward trade retaliation, there are growing calls for a negotiated solution similar to the one reached with the UK.
The UK may have shown us the model
The U.S.–UK agreement connected pharmaceutical pricing directly with trade.
The UK agreed to increase the net price paid by the NHS for prospective new medicines by 25 percent, increase spending on new medicines over time and limit certain pharmaceutical repayment rates. In return, the United States provided significant protections from pharmaceutical tariffs.
Importantly, the agreement itself connects those commitments to U.S. Most Favored Nation policies.
That makes what is happening with Germany worth watching.
In July, I discussed this possibility with Melanie Whittington at the Leerink Center for Pharmacoeconomics. We talked about whether the U.S.–UK arrangement could become a template for Germany.
My view was that it could be a political template, but Germany would be a harder test. Germany has a different statutory reimbursement system, operates through AMNOG and sits within the European Union.
We may now be seeing that test begin.
Where does MFN fit?
The basic argument behind MFN is relatively simple.
The United States believes Americans pay too much for medicines while other wealthy countries pay too little, leaving the U.S. market carrying a disproportionate share of the cost of pharmaceutical innovation.
There are two ways to narrow that gap.
Washington can try to bring American prices closer to those paid overseas. Or it can try to move prices overseas closer to those paid in America.
The UK agreement demonstrates that Washington is willing to work on the second side of that equation. The Germany investigation may tell us whether that approach can be repeated.
That does not mean Section 301 is MFN. Nor has USTR announced that trade enforcement is the mechanism through which MFN will be implemented.
But it raises an important possibility: trade policy may become one of the tools Washington uses to pursue the broader economic objective behind MFN.
Why should executives care?
If you run a pharmaceutical or biotech company, this changes the way international pricing risk should be viewed.
Germany is still Germany. The UK is still the UK. France, Italy, Spain and other markets continue to have their own reimbursement systems, budget pressures and approaches to determining value.
Those decisions may no longer remain entirely within those national systems.
U.S. trade policy could become another factor.
That has potential implications for launch sequencing, market access, reference pricing, revenue assumptions and investment decisions. A decision that once looked like a German reimbursement issue could eventually have consequences for a company's broader global strategy.
If Germany ultimately reaches an arrangement resembling the UK deal, the obvious question will be what country comes next.
The bigger signal
This is the type of development we look at closely at Lanton Strategies International.
Not because every Section 301 investigation will change pharmaceutical markets, but because understanding what is happening often requires looking across policy silos.
MFN looks like U.S. drug pricing policy. AMNOG looks like German reimbursement policy. Section 301 looks like trade policy. The U.S.–UK agreement looks like a bilateral trade arrangement.
The important part is the connection between them. What happens in reimbursement is beginning to influence trade policy, and trade policy may, in turn, influence how countries approach drug pricing.
We do not yet know whether Germany will result in another UK-style agreement. But if it does, pharmaceutical executives may need to reconsider how they think about global pricing risk.
The bigger question we have to consider is how Washington brings prices overseas closer to those paid in the United States.
Independent analysis from Lanton Strategies International. This article does not constitute legal advice.
Congress Is Exploring Whether Medicare Can Incentivize Domestic Drug Manufacturing
A bipartisan Senate proposal would direct CMS to explore whether Medicare reimbursement could help strengthen domestic pharmaceutical manufacturing. While the bill does not change payment policy, it reflects a broader question with significant strategic implications: could reimbursement become another tool for shaping manufacturing investment and supply chain resilience?
Pharmaceutical manufacturing has traditionally been influenced by trade policy, tax incentives, and government investment. A new bipartisan Senate proposal suggests Congress is considering another lever: whether Medicare reimbursement could help encourage domestic drug manufacturing.
Legislation introduced by Sens. Adam Schiff, Democrat of California, and Rick Scott, Republican of Florida, would direct the Centers for Medicare and Medicaid Services to examine how its drug coverage and reimbursement authorities could reduce U.S. reliance on foreign pharmaceutical manufacturers. CMS would report its findings to Congress and could recommend reimbursement approaches that support domestic production of active pharmaceutical ingredients, key starting materials, and other critical pharmaceutical inputs.
The bill does not change Medicare payment policy. Instead, it asks whether Medicare's purchasing power could become part of a broader strategy to strengthen the pharmaceutical supply chain.
That question is significant.
For decades, manufacturing policy has largely been shaped through trade measures, grants, and tax incentives. This proposal introduces the possibility that healthcare reimbursement could also influence where pharmaceutical products are manufactured. If reimbursement eventually recognizes domestic production or supply chain resilience, manufacturing decisions could carry implications beyond cost and operational efficiency.
The proposal also reflects a broader policy trend. Governments are increasingly treating pharmaceutical manufacturing as strategic infrastructure rather than simply a commercial activity. The European Union's Critical Medicines Act pursues similar objectives through different policy mechanisms, highlighting a growing international focus on supply chain resilience.
Whether or not this legislation advances, it reflects a broader shift in policymaking. Manufacturing strategy is no longer being shaped solely by operations, trade, and tax policy. Congress is beginning to explore whether healthcare reimbursement should become part of that equation as well.
For pharmaceutical companies, the legislation is less important than the question it asks. If reimbursement policy eventually becomes another tool for strengthening domestic manufacturing, market strategy, capital planning, and manufacturing decisions may become more closely connected than they have been in the past.
At Lanton Strategies International, these are the kinds of intersections we focus on: where reimbursement, trade policy, industrial strategy, and commercial decision making begin to shape one another.
LSI Insight: This article reflects the independent analysis of Lanton Strategies International regarding emerging policy developments and their potential implications for healthcare, life sciences, and health technology organizations. It is intended for informational purposes only and should not be construed as legal, regulatory, or policy advice.
What a Potential AstraZeneca and Bristol Myers Squibb Deal Says About Global Pharma Strategy
A potential AstraZeneca and Bristol Myers Squibb combination highlights the strategic pressures reshaping global pharmaceuticals, including patent exposure, United States market access, regulatory review, portfolio overlap, and whether greater scale can deliver sustainable commercial value.
The reported possibility of a combination between AstraZeneca and Bristol Myers Squibb highlights the strategic pressures shaping the pharmaceutical industry.
For Bristol Myers Squibb, a transaction could provide greater stability as several major products approach patent expiration. For AstraZeneca, the appeal would include deeper access to the United States market and a broader portfolio across oncology, cardiovascular medicine, hematology, and cell therapy.
The challenge is that greater scale does not automatically produce greater value. A transaction of this size would require the companies to manage extensive therapeutic overlap, global regulatory review, integration risk, and the possibility that required divestitures could weaken the strategic rationale for the deal.
Ron Lanton recently discussed these issues with Pharmaceutical Executive, including how regulators may evaluate competing products and pipeline programs, which shareholders could benefit most, and why the United States, European Union, and United Kingdom may approach the transaction differently.
The broader lesson is that pharmaceutical mergers are no longer simply questions of product portfolios and purchase price. They are also questions of patent exposure, market access, regulatory strategy, research priorities, and whether global scale can translate into sustainable commercial value.
Read the full Pharmaceutical Executive conversation here.
Generic Drug Tariffs Are Not Yet Policy. Companies Still Need a Plan
President Trump has announced a potential tariff schedule for imported generic drugs, but no executive order, Federal Register notice, tariff amendment, or implementation guidance has been issued. Companies should not treat the proposed rates as current policy, but manufacturers, distributors, health systems, pharmacies, and investors should begin evaluating their supply-chain and commercial exposure.
President Trump has announced that imported generic drugs would remain subject to a zero tariff for two years beginning August 1, 2026. The tariff would then rise to 100% for one year and 200% thereafter. The stated objective is to encourage more pharmaceutical manufacturing in the United States.
The announcement has generated immediate concern about drug prices, shortages, and the exposure of manufacturers that rely heavily on production outside the United States.
There is an important distinction, however, between a policy announcement and an enforceable tariff.
As of July 23, 2026, no new executive order, presidential proclamation, Federal Register notice, Customs and Border Protection guidance, or amendment to the Harmonized Tariff Schedule has been issued to implement the announced generic-drug tariffs.
The existing legal position still says the opposite. The pharmaceutical tariff proclamation issued in April expressly provides that generic pharmaceuticals, biosimilars, and their associated ingredients are not subject to Section 232 tariffs “at this time.” It directs the Secretary of Commerce to continue monitoring generic imports and report within one year on whether additional action may be appropriate.
The announced tariff schedule should therefore be treated as a serious business signal, not as an operative legal obligation.
The Details Will Determine the Real Exposure
Any implementing action would need to answer questions that could materially change its commercial effect.
Would the tariffs apply only to finished generic drugs, or also to active pharmaceutical ingredients and key starting materials? Would biosimilars remain within the generic category? How would the government determine a product’s country of origin when different manufacturing stages occur in different jurisdictions?
It is also unclear whether manufacturers could qualify for lower rates by building or expanding U.S. production. The existing branded-pharmaceutical tariff framework provides different treatment for certain companies with approved onshoring plans, pricing agreements, or operations in countries covered by trade arrangements. Companies should not assume that the same structure will automatically be extended to generics.
Until those details are established, manufacturers cannot calculate their potential tariff liability. Distributors, pharmacies, health plans, and healthcare providers also cannot determine how additional costs might move through the supply chain.
Generic-Drug Economics Make the Risk Different
Generic drugs frequently operate under narrow margins, competitive purchasing contracts, and reimbursement structures that may not adjust quickly when acquisition costs rise.
A manufacturer may not be able to absorb a substantial tariff. It may also lack the contractual ability to pass the full cost to a wholesaler or customer.
For some products, the response may not simply be a higher price. Manufacturers could reconsider whether it remains economically viable to continue supplying a particular drug to the U.S. market.
That creates a potential availability risk, especially for low-margin products, drugs with few suppliers, and medicines already vulnerable to shortage.
Reshoring could strengthen pharmaceutical supply chains over time. Tariffs alone, however, do not resolve the capital, workforce, regulatory, contracting, reimbursement, and purchasing challenges that determine whether domestic generic manufacturing is commercially sustainable.
What Companies Should Do Now
Companies should not treat the announced rates as settled policy or make definitive customs conclusions before formal implementation documents are issued. They should, however, begin evaluating their potential exposure now.
Generic manufacturers and importers can begin mapping products by manufacturing location, ingredient source, country of origin, margin, tariff classification, and contractual ability to pass through higher costs.
Distributors, pharmacies, health plans, and health systems should identify products for which a tariff could create the greatest cost or availability risk.
Investors should evaluate which companies possess credible domestic manufacturing options and which remain dependent on policy exemptions or continued access to lower-cost foreign production.
Leaders should also model several possible outcomes, including:
Continued exemption for generic drugs
Tariffs limited to selected products, ingredients, or countries
Reduced rates for companies making approved U.S. manufacturing commitments
Broader tariffs covering both finished products and pharmaceutical ingredients
Each scenario could produce different decisions involving sourcing, inventory, contracts, capital investment, pricing, and continued participation in the U.S. market.
The tariff is not yet policy. The strategic question is whether companies will understand their exposure before it becomes one.
Lanton Strategies International advises healthcare, life-sciences, and investment organizations on how trade policy, regulation, reimbursement, market access, and capital developments affect business strategy and commercial execution across the United States, European Union, and United Kingdom.
The New Risk Map for Pharmaceutical Pricing
Pharmaceutical pricing is becoming part of a broader cross-border risk conversation. The U.S. Section 301 investigation into Germany’s pricing and reimbursement practices shows why companies and investors need to view pricing, reimbursement, trade policy, launch planning, and patient access together.
I was grateful to join Melanie Whittington, PhD on Perspectives by the Leerink Center for Pharmacoeconomics for a conversation about the U.S. Trade Representative’s Section 301 investigation into Germany’s pharmaceutical pricing and reimbursement practices. The interview can be found here.
The investigation itself is important, but I think the larger point is even more important.
The status quo is over.
Pharmaceutical companies and investors can no longer look at pricing, reimbursement, trade policy, launch planning, manufacturing, and patient access as separate issues. These areas are beginning to move together, especially for companies operating across the U.S., EU, and UK.
For a long time, pharmaceutical pricing was mostly treated as a domestic reimbursement issue. In the United States, that meant looking at Medicare, CMS, PBMs, commercial payers, the Inflation Reduction Act, and state-level access questions. In Europe, it meant looking country by country at health technology assessment, national budgets, reimbursement decisions, and launch sequencing.
Those issues still matter. They always will. The difference now is that trade policy is becoming part of the pricing conversation.
Section 301, Section 232, Most Favored Nation-style proposals, tariff discussions, and cross-border pricing arrangements are forcing companies to think differently about market strategy. A pricing decision in one country may no longer stay in that country. A reimbursement proposal in Europe may become part of a broader U.S. trade discussion. A launch strategy that once looked commercially sound may need to be reconsidered through a geopolitical and policy lens.
That is especially important because the EU is not a monolith. The European Union may operate as a commercial bloc in certain contexts, but pharmaceutical pricing and reimbursement remain deeply national. Germany, France, Italy, Spain, the Netherlands, and other countries each bring their own budget pressures, political expectations, health system priorities, and views of value.
That is why it is too simple to say that Europe is just about “price controls.” Pricing decisions are tied to clinical value, budget impact, insurance systems, patient access, politics, and long-term health system planning. Once trade policy enters that discussion, the risk map changes.
This matters for executives, boards, and investors. A company may have strong science, promising clinical data, and a compelling patient story. Those things are essential, but they are no longer enough on their own.
The company also has to explain where it will launch, how it expects to be reimbursed, what pricing assumptions support the business model, how those assumptions could change, and whether trade or policy pressure could affect the commercial plan. These questions matter even for biotech companies that are years away from commercialization because many of the assumptions about market size, pricing, access, manufacturing, and return on investment are made long before launch.
The patient access question cannot be separated from this either. If pricing and trade disputes create uncertainty, companies may delay launches, rethink markets, or narrow their commercial strategy. That can affect whether patients get access to innovative therapies, when they get access, and where that access happens first.
At the same time, policymakers are under pressure to make medicines more affordable and health systems more sustainable. That pressure is not going away.
That is why the next phase of pharmaceutical strategy requires a more connected view. Drug pricing is not only a reimbursement issue. Trade policy is not only a government relations issue. Market access is not only a commercial issue. Investor risk is not only a finance issue.
These issues now move together.
At Lanton Strategies International, we are watching these developments because they sit at the intersection of policy, reimbursement, trade, market access, and capital strategy across the U.S., EU, and UK.
For pharmaceutical companies, biotech executives, investors, and health-sector leaders, the question is not whether the rules are changing.
They are.
The work now is understanding what comes next.
Germany’s Drug Pricing Dispute Now Has a Comment Deadline. Stakeholders Should Pay Attention.
The USTR’s Section 301 investigation into Germany’s pharmaceutical pricing and reimbursement practices has moved from policy signal to active comment opportunity. With written comments due August 10, 2026, German life sciences companies, investors, and associations should consider how the investigation may affect pricing strategy, market access, innovation, and cross-border investment.
Germany’s pharmaceutical pricing and reimbursement system has moved into a new arena.
In June 2026, the Office of the United States Trade Representative launched a Section 301 investigation titled “Germany’s Persistent Underpayment for Innovative Pharmaceutical Products.” The investigation focuses on whether Germany’s pharmaceutical pricing and reimbursement practices may be unreasonable, discriminatory, or burdensome to U.S. commerce.
The USTR comment docket opened on June 25, 2026. Written comments are due by August 10, 2026, at 11:59 PM EDT.
For German companies, investors, trade associations, and policymakers, this should not be viewed as a routine U.S. trade development.
It is a signal that drug pricing is becoming part of international economic policy.
For many years, pharmaceutical pricing was treated primarily as a domestic healthcare issue. Germany had its system. The United Kingdom had its system. France, the Netherlands, Italy, Spain, and other countries had their own reimbursement frameworks.
Companies still had to understand each market on its own terms. Germany was different from the UK. France was different from the Netherlands. Pricing and reimbursement strategy had to account for those differences, but the debate usually stayed inside the healthcare policy framework.
That is starting to change.
The U.S. government is now using a trade law mechanism to scrutinize how another advanced economy pays for innovative medicines. That does not mean the United States will automatically prevail. It also does not mean Germany will suddenly redesign its statutory health insurance system around U.S. objections.
It does mean the policy risk has changed.
Germany matters because it is one of Europe’s most important pharmaceutical markets. Decisions made in Germany can affect launch sequencing, reference pricing, investor assumptions, and commercial planning across multiple markets.
The U.S. argument appears to be that American patients and the U.S. market are carrying too much of the global cost of pharmaceutical innovation while other wealthy countries use reimbursement systems to pay less.
German and European policymakers are likely to see the issue very differently. From their perspective, pharmaceutical reimbursement is part of national healthcare policy, public budgeting, and statutory insurance design.
That tension is exactly why this investigation matters.
For German life sciences companies and investors, the issue is not only whether this ends with tariffs, negotiations, or no immediate action.
The more important point is that pharmaceutical pricing is being pulled into a wider conversation about trade, investment, reimbursement, and market access.
That has practical consequences. A German pricing decision may no longer stay inside Germany. It can affect launch strategy, investor assumptions, reference pricing, and how policymakers in Washington view the balance between innovation, access, and cost.
The USTR comment period gives stakeholders an opportunity to shape the record. A strong submission should not simply defend or criticize German pricing policy. It should explain the commercial, legal, reimbursement, innovation, and patient-access consequences in a way that U.S. trade policymakers can understand.
At Lanton Strategies International, we help companies, investors, and associations understand how policy developments across the U.S., EU, and UK affect market strategy, pricing risk, reimbursement positioning, and capital planning.
For stakeholders considering whether to submit comments, we can help assess the USTR investigation, develop comment strategy, identify the business and policy issues that should be raised, and translate German reimbursement concerns into the language of U.S. trade policy.
The Germany Section 301 investigation is one of those moments where healthcare policy, trade policy, and commercial strategy are no longer separate conversations.
For German life sciences companies, investors, and associations, the time to assess the issue is now.
When Drug Pricing Becomes a Trade Dispute
The U.S. Section 301 investigation into Germany’s pharmaceutical pricing and reimbursement policies shows how quickly healthcare cost-containment can become a trade enforcement issue. For life sciences companies operating across the Atlantic corridor, pricing policy, market access, reimbursement strategy, and geopolitical risk are becoming part of the same commercial planning conversation.
The United States has launched a Section 301 investigation into Germany over pharmaceutical pricing and reimbursement policies, with USTR characterizing the issue as “persistent underpayment for innovative pharmaceutical products.”
For multinational pharmaceutical and biotech companies operating across the Atlantic corridor, this is an important regulatory and market access signal.
The investigation appears tied to German healthcare cost-containment legislation that could further reduce spending on innovative medicines. While the trade process may take time to unfold, the larger issue is already clear: domestic healthcare pricing policy is now being viewed through a trade enforcement lens.
That matters because Germany is not just another European market. It is one of the most important pharmaceutical markets in Europe, and its reimbursement policies can influence launch sequencing, pricing strategy, and broader European market planning.
For life sciences companies, this creates a new layer of uncertainty. Pricing, reimbursement, intellectual property protection, market access, and trade enforcement are no longer separate conversations. They are becoming part of the same commercial risk analysis.
The investigation also reflects a broader U.S. policy argument: American patients and companies should not carry a disproportionate share of the global cost of pharmaceutical research and development while other wealthy markets use aggressive reimbursement controls to limit spending.
This does not mean tariffs are inevitable. USTR has suggested that the issue could potentially be resolved through negotiations, including a path that expands access to innovative medicines while ensuring fair reimbursement for pharmaceuticals made by American workers. Still, the use of Section 301 against Germany is significant because it shows how quickly pricing policy can become a trade dispute.
For pharmaceutical and biotech companies, the takeaway is clear. Market-entry strategy cannot focus only on regulatory approval or clinical value. It also has to account for how governments use pricing rules, budget controls, and trade tools to shape the value of innovation.
This is exactly the type of geopolitical and market access risk we track closely at Lanton Strategies International. As pricing policy and international trade enforcement continue to intersect, companies will need to think more carefully about where they launch, how they price, and how policy risk affects long-term commercial planning.
When Procurement Policy Becomes Market Strategy
The UK’s new value-based procurement guidance for medical technology shows how healthcare purchasing is becoming a market strategy issue. For companies entering or scaling across the UK, U.S., and European markets, evidence of system-level value is becoming central to adoption and growth.
The UK Government’s new guidance on value-based procurement for medical technology is worth paying attention to.
At first glance, this may seem like a procurement update. I see it as something larger: a signal about how healthcare systems are starting to connect purchasing decisions with market access, adoption, and long-term value.
For medtech, digital health, diagnostics, AI, and other healthcare technology companies, the message is pretty clear. It is no longer enough to show that a product works, that it is innovative, or that it comes in at a competitive price.
The NHS is moving toward a broader way of measuring value.
That means companies will need to explain how their products fit into the health system itself. Does the product improve the patient pathway? Does it reduce pressure on clinicians and staff? Does it create value beyond the initial purchase price?
Healthcare systems are under pressure everywhere. They are dealing with workforce shortages, budget constraints, supply chain concerns, and rising expectations from patients and policymakers.
Even with political change in the UK, the larger direction is still important for companies to understand. Healthcare systems are under pressure to show value, manage cost, and make purchasing decisions that support adoption across the system.
A product that can help solve those problems will be viewed differently than a product that only competes on cost.
Procurement is becoming less about the cheapest available option and more about whether a product can be adopted, used, funded, and scaled within the system. For companies entering the UK market, that changes how they should think about evidence, reimbursement, commercial planning, and market access.
It also matters for companies looking across the U.S., UK, and European markets. Approval is important, but approval alone does not create adoption. Companies need to be able to show why their product belongs inside the system and how it supports the larger goals of that system.
This is the type of shift companies should not treat as background policy. It can affect how a product is positioned, how evidence is developed, and how market entry is planned.
When procurement frameworks start measuring broader value, they do more than guide purchasing decisions. They shape how companies position themselves, how investors assess opportunity, and how healthcare innovation actually reaches the market.
For companies trying to enter or expand in healthcare markets, procurement cannot be treated as a back-office issue anymore. It is becoming part of the strategy.
Beyond the Deal Activity: Strategic Questions Emerging from Global Pharmaceutical R&D
Pharmaceutical innovation is becoming increasingly global, but bringing new therapies to market requires more than scientific success. As healthcare companies expand cross-border partnerships and licensing activity, executives must also navigate reimbursement systems, trade policy, market access challenges, and geopolitical considerations that shape commercial outcomes.
A recent Pharmaceutical Executive article seen here examined China's growing role in pharmaceutical R&D and licensing activity. I was pleased to contribute to that discussion, which highlights an important trend shaping the future of healthcare and life sciences.
The growth in cross-border pharmaceutical partnerships reflects a broader reality: innovation is becoming increasingly global. Scientific talent, clinical development capabilities, manufacturing capacity, and investment opportunities are no longer concentrated in a single market. Pharmaceutical companies are evaluating opportunities wherever they believe innovation can be developed efficiently and brought to patients successfully.
While much attention is understandably focused on the volume of deal activity, the more interesting questions may lie beneath the transactions themselves.
Healthcare executives and investors are increasingly evaluating factors that extend beyond the science. Reimbursement environments, market access pathways, trade policy, industrial strategy, supply chain resilience, and geopolitical developments are all becoming part of the strategic conversation.
The challenge is that scientific innovation and commercial success do not always follow the same path.
A promising therapy may emerge from one market, attract investment from another, undergo clinical development across multiple regions, and ultimately depend on regulatory approvals, reimbursement decisions, and commercialization strategies in entirely different jurisdictions. The path from discovery to patient access is becoming more interconnected and, in many cases, more complex.
For healthcare and life sciences leaders, this raises several important questions.
How should companies evaluate policy risk alongside scientific opportunity?
How should investors think about reimbursement uncertainty when assessing long-term value?
How should organizations balance global sourcing of innovation with evolving national priorities related to healthcare security, industrial policy, and supply chain resilience?
These questions do not diminish the importance of scientific innovation. Rather, they recognize that innovation alone is not always sufficient to determine market success.
As pharmaceutical development becomes more global, the healthcare organizations that succeed may be those that understand both the science and the broader strategic environment in which that science operates.
The Pharmaceutical Executive article is a valuable contribution to this discussion and highlights an important development that healthcare leaders should continue to watch closely. The implications extend well beyond individual transactions and point toward a healthcare market that is becoming increasingly interconnected across innovation, policy, capital, and commercialization.
The EU’s Tech Sovereignty Package Is a Market Strategy Issue
Europe’s Tech Sovereignty Package is more than a digital policy announcement. For healthcare, life sciences, healthtech, AI, cloud, and data infrastructure companies operating across the U.S., UK, and EU, it signals a broader shift in market access, resilience planning, procurement strategy, and cross-border risk.
The European Commission’s new European Technological Sovereignty Package should not be read as another routine digital policy announcement. It is better understood as part of a broader move by Europe to reduce dependence on external technology providers, build domestic capacity, and give European institutions, companies, and public bodies more control over the infrastructure that will shape the next phase of the digital economy.
For companies operating across the U.S., UK, and EU, especially in artificial intelligence, cloud computing, semiconductors, open-source software, healthtech, life sciences, and data infrastructure, this is now a market access issue.
Europe is making clear that digital infrastructure is becoming part of industrial policy, resilience planning, procurement strategy, and geopolitical risk management.
The package includes Chips Act 2.0, the Cloud and AI Development Act, an EU Open Source Strategy, and a Strategic Roadmap for Digitalisation and AI in Energy. Together, these measures are intended to strengthen Europe’s position in semiconductors, cloud, AI, and open-source technologies, while reducing structural dependencies on non-EU providers.
For years, many non-EU companies approached Europe through a familiar lens. The main questions were data privacy, regulatory compliance, competition rules, and local market adaptation. Those issues still matter, but Europe is now asking a larger question: who controls the technology, data, infrastructure, and supply chains that its economy and public services rely on?
This does not mean Europe is closing itself off from U.S. or other non-EU companies. That would be too simplistic. The better reading is that Europe is hedging.
Countries are not necessarily abandoning U.S. technology, U.S. platforms, or U.S. partners. They are planning for a world where dependence on any single outside market, supplier, cloud infrastructure, policy environment, or geopolitical relationship carries more risk than it used to.
For healthcare, life sciences, and healthtech companies, this should be taken seriously. Digital infrastructure is now tied directly to clinical operations, patient data, diagnostics, AI-enabled decision support, hospital workflow, research platforms, energy reliability, and public-sector trust. These are not abstract technology debates. They affect how companies enter markets, structure partnerships, raise capital, select vendors, and explain their long-term resilience to customers and investors.
The market access questions are changing.
Where is your infrastructure hosted? How much of your product depends on non-EU cloud capacity? How resilient is your semiconductor or hardware supply chain? Can your software architecture support interoperability and openness where European buyers expect it? Can your company explain how it fits within Europe’s digital sovereignty agenda without appearing misaligned with it?
These questions will not be answered by legal compliance.
They require a broader strategy that connects policy, procurement, infrastructure, investor risk, and commercial positioning. A company may be technically compliant and still be poorly positioned for where the market is moving. That is especially true in sectors where governments are major purchasers, regulators, funders, or strategic partners.
The practical lesson is straightforward: policy is now part of the business plan.
Europe is building a digital ecosystem designed to increase resilience and reduce strategic dependence. Companies that understand that trajectory early will be better positioned to enter, grow, partner, and compete. Companies that treat it as just another regulatory announcement may miss the broader market signal.
Lanton Strategies International advises cross-border healthcare, life sciences, healthtech, and technology companies on U.S., UK, and EU policy, regulatory risk, market-entry strategy, and commercial positioning.
“Buy European” Is Becoming a Healthcare Market Strategy
Europe’s critical medicines agreement shows how healthcare market strategy is becoming more closely tied to procurement, manufacturing capacity, supply-chain resilience, and policy risk. For healthcare, life sciences, medtech, diagnostics, and pharmaceutical companies looking across the U.S., UK, and EU, “Buy European” may become more than a procurement phrase. It may become a market-entry strategy question.
Europe’s latest agreement on critical medicines deserves more attention from companies looking at the EU market.
The immediate issue is medicine shortages. That matters on its own. Health systems need reliable access to essential medicines. Patients need confidence that the products they depend on will be available. Governments are under pressure to reduce the risk of disruption, especially after several years of pandemic shocks, geopolitical tension, supply-chain strain, and growing concern about overdependence on production outside Europe.
The business strategy side may prove just as important.
The European Parliament’s recent announcement on critical medicines points toward a more assertive European approach to healthcare supply. The agreement is designed to reduce dependency on non-EU countries, strengthen the EU pharmaceutical sector, encourage joint procurement, and support a “Buy European” approach in certain procurement settings.
This is important for healthcare and life sciences companies.
It suggests that Europe is thinking about medicines through a wider strategic lens. Availability, manufacturing capacity, procurement, competitiveness, and supply-chain resilience are moving closer together. A company entering the EU market may begin with regulatory questions, but the commercial strategy has to go further.
Where is the product made? How resilient is the supply chain? How exposed is the company to third-country dependencies? How will procurement bodies view the product? Does the company’s market presence fit the direction European policymakers are trying to move?
Those questions are becoming part of the market-entry conversation earlier than they used to.
That does not mean Europe is closing itself off. It does mean companies should pay closer attention to how policy language is changing.
For years, many companies looked at international growth through familiar categories. Regulatory approval was one workstream. Reimbursement was another. Distribution sat somewhere else. Capital strategy often moved on its own track. That approach is becoming harder to sustain in healthcare.
The EU’s critical medicines agenda shows why.
A medicine shortage is not only a supply problem. It can become a procurement problem, a manufacturing problem, a pricing problem, a political problem, and eventually a market-access problem. Once governments begin treating supply resilience as part of public health policy, companies have to think differently about how they position themselves in the market.
This is especially important for pharmaceutical, medtech, diagnostics, and life sciences companies operating across the U.S., UK, and EU.
In the U.S., companies already have to think through FDA expectations, CMS reimbursement, payer adoption, pricing pressure, investor scrutiny, and the operational realities of commercialization. In Europe, the conversation increasingly includes EU-level pharmaceutical reform, national reimbursement systems, procurement decisions, industrial capacity, and supply-chain resilience. In the UK, life sciences policy is also being tied more directly to economic growth, manufacturing, innovation, and health system transformation.
That creates a different kind of strategy question.
A company may have a strong product and still face problems if the strategy does not account for how the product will be paid for, purchased, distributed, manufactured, and supported. A diagnostics company may need to think about evidence, reimbursement, clinical workflow, and procurement at the same time. A medtech company may need to understand hospital adoption, distribution infrastructure, regulatory expectations, and investor assumptions before choosing how to expand. A pharmaceutical company may need to evaluate whether its manufacturing footprint and supply-chain design fit a market where governments are paying closer attention to resilience.
This is where the “Buy European” language becomes important.
It is not only a phrase about procurement. It is a sign of where healthcare strategy is heading. Europe is placing more value on supply security, industrial capacity, and strategic resilience. Companies do not have to overreact to that, but they should not ignore it.
For U.S. companies looking at Europe, this means the EU market should be viewed as more than another regulatory and commercial opportunity. It is a market shaped by public health priorities, national health systems, EU industrial policy, and growing concern about dependency.
For European companies looking at the U.S., the lesson runs in the other direction. The U.S. opportunity may be large, but it comes with its own policy, reimbursement, pricing, and capital-market pressures.
The practical takeaway is simple: healthcare market entry has to be built earlier and more realistically.
Regulatory clearance or approval remains important, but it does not answer enough of the business questions. The better strategy begins before launch, before fundraising assumptions are locked in, and before companies commit to a market pathway that may not match how the market is actually evolving.
The companies that manage this well will understand the policy environment before it becomes a commercial problem. They will pay attention to how governments are defining resilience. They will think through procurement, supply chains, reimbursement, and market access early enough to make better decisions.
Europe’s critical medicines agreement is an early signal worth watching.
“Buy European” may sound like a procurement preference. For healthcare and life sciences companies, it may also become a market strategy question.
Where Healthcare Capital Is Moving in Europe
A review of Europe’s largest healthtech funding rounds in 2025 reveals a broader shift in where healthcare capital is concentrating. Investors increasingly appear focused on scalable infrastructure, operational efficiency, AI enabled platforms, and healthcare systems capable of adapting to growing regulatory and financial pressure across global markets.
One of the more interesting healthcare trends developing in Europe is where capital is actually concentrating.
A recent review of the largest European healthtech funding rounds of 2025 showed capital flowing heavily toward AI enabled drug discovery, robotic surgery, preventative diagnostics, digital care infrastructure, and operational healthcare platforms. Companies like Oura, Isomorphic Labs, CMR Surgical, Neko Health, and Cera reflect something larger than isolated growth stories.
The broader pattern is that investors increasingly appear focused on scalable healthcare infrastructure rather than standalone point solutions. Many of the companies attracting the largest rounds are positioned around operational efficiency, data integration, workforce pressure, preventative models, or clinical workflow acceleration.
That matters strategically because healthcare systems across both the U.S. and Europe are operating under growing reimbursement pressure, labor constraints, and regulatory complexity at the same time AI capabilities are accelerating.
Healthcare innovation is increasingly becoming a question of operational scalability, regulatory adaptability, and infrastructure resilience — not simply technological novelty.